How we invest
A fund that prices what others cannot
Austral Anchor invests in technology, science, and market opportunities where the consensus is measurably wrong. The essay above is the current thesis. These are the rules underneath it.
- Parable of talents
- Capital exists to be put to work. We invest in the people and industries with the most engineering talent per dollar, which today means the Chinese supply chain and the Western companies that consume its output.
- Critical infrastructure
- Reducers, magnets, screws, sensors, compute. The unglamorous layers that every robot, car, and data centre is built from, bought where the localisation rate is low and the pricing power is high.
- Short-term arbitrage
- The same component sells at Chinese cost and Western price. When a gap like that is visible in public filings and nobody has built the table, that is the trade.
- No leverage, ever
- The thesis being right and the position surviving are different problems. No borrowed money, position caps, and a drawdown covenant written into the documents before the first outside dollar.
Portfolio construction
Own the slow steps. Never borrow to do it.
The book that falls out of the essay, with target ranges. Weights move with the localisation data, not with the news. Single positions are capped at 7%. The fund goes to half exposure at a 20% drawdown and to cash at 30%, by covenant, enforced by a risk manager who is not the portfolio manager.
| Sleeve | What it holds | Range |
|---|---|---|
| Bottleneck components | Roller screws, force/torque sensors, RV reducers. High import dependency, credible domestic challenger, in every unit. | 25–35% |
| Export arbitrage | Chinese component makers with meaningful Tesla, Figure, 1X, or European revenue. Western prices on Chinese costs. | 15–25% |
| Chokepoints | Rare-earth magnets on both sides of the export-control line; lithography, substrate, and grid equipment suppliers to the Chinese buildout. | 15–20% |
| Precision pairs | Long the Chinese challenger, short the Japanese incumbent, per component. The localisation rate decides. | 5–10% |
| Slow-step compressors | Firms shortening trials, fabrication, or permitting in an AI-compressed field. Sized up as evidence arrives. | 5–15% |
| Developed-world deployers | Logistics, care, and construction operators positioned to buy $14,000 robots. Optionality until the nail is hammered. | 0–10% |
| Cash | Treasury bills. The reason no prime broker can ever make a decision for us. | ≥10% |
Who runs it
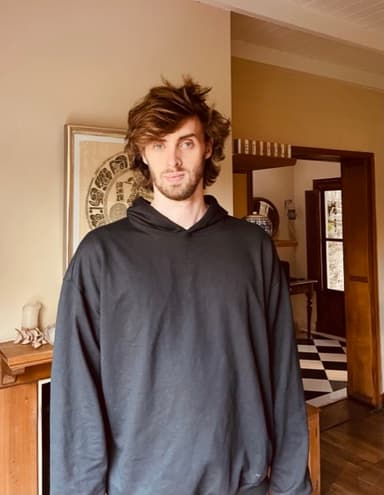
Santy Gegenschatz
Economist and software engineer. BSc in Economics, magna cum laude, at 20. Google at 21. Left at 23 to build. Founder since 2024 of Antbuilder, a studio running several products in parallel, of which Austral Anchor is the one that prices the world.
- BSc Economics, magna cum laude · 2018
- MSc Finance · 2020
- Software engineer · 2023
- Founder, Antbuilder · 2024 to date
Invest with us
Selective by design
We work with a small number of investors who share the thesis and can hold through a drawdown. Minimum commitment is $500,000. Leave your details and we reply within 24 hours.
Selected reading
Books behind the thinking
- Sapiens: A Brief History of HumankindYuval Noah Harari
- Principles: Life and WorkRay Dalio
- The Innovator's DilemmaClayton M. Christensen
- Thinking, Fast and SlowDaniel Kahneman
- The Black SwanNassim Nicholas Taleb
- Guns, Germs, and SteelJared Diamond